
By Sylvia Namukose
- Advertisement -
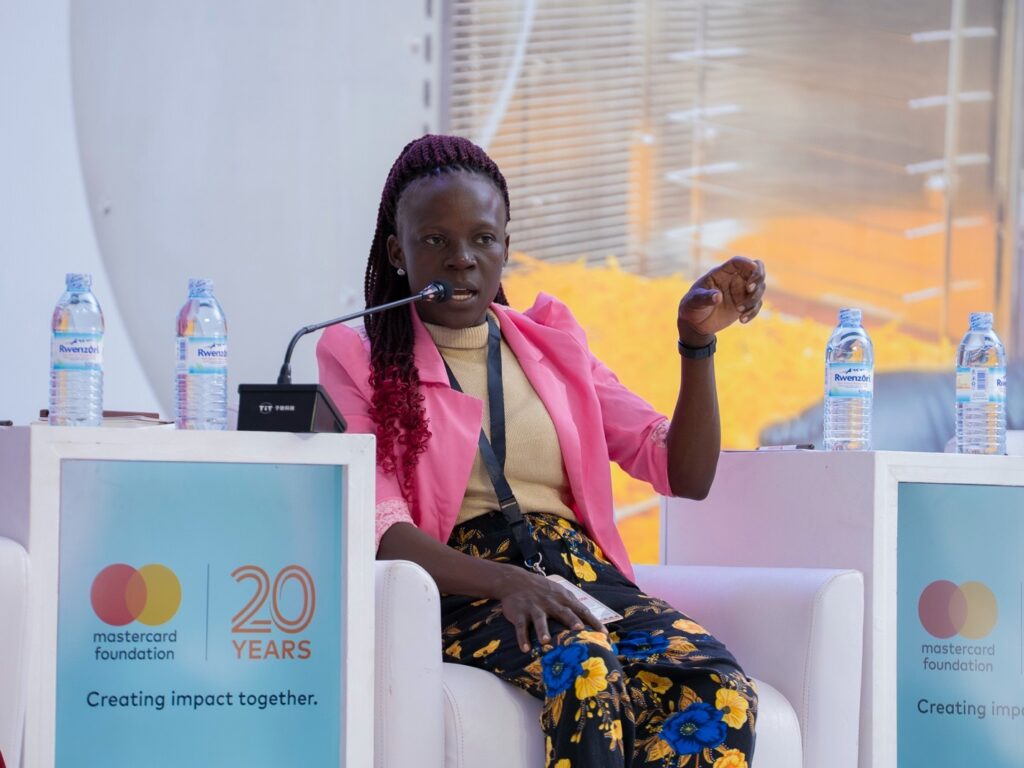
When I received my first loan of UGX 1 million through Centenary Bank, with support from the Stimulating Agribusiness for Youth Employment (SAYE) project, implemented by Heifer International and the Mastercard Foundation. I was cultivating one acre of rented land, mainly to produce food for household consumption. I was also working as a nursery schoolteacher, and farming was something I did alongside my job rather than a business I could depend on for a livelihood.
I repaid that first loan and subsequently accessed and repaid additional financing. Today, I cultivate four acres, own oxen and poultry, and am better placed to support my family. Access to credit, combined with knowledge about managing and investing money, helped me expand my farming activities.
But my experience has taught me that financial inclusion is about more than receiving a loan. It is about having the opportunity to access finance fairly, make decisions about how to use it and benefit from the returns. It is about having the freedom to determine what to do with the resources available to you and the confidence to build on what you earn.
For many women in Uganda, that freedom remains constrained by social expectations, institutional practices and unequal access to productive assets.
In communities across Busoga and other parts of the country, women’s economic choices are often influenced by expectations about property ownership, household responsibilities and financial decision-making. In some households, land and other valuable assets are traditionally registered in men’s names. Women may also be expected to consult their husbands or male relatives before making significant financial decisions.
Although these practices vary across families and communities, their economic implications are significant. Women who do not own land or other acceptable collateral may struggle to qualify for loans. Those with limited control over household income may also find it difficult to make independent decisions about saving, borrowing or reinvesting in their businesses.
These challenges can extend into the financial sector. A woman may have a viable business and the ability to repay a loan but still encounter lending requirements that do not recognise her circumstances. For women with disabilities, inaccessible banking facilities, communication barriers and assumptions about their capabilities can create additional obstacles.
This raises an important question: how inclusive is a financial system if women can access its products in theory but cannot independently qualify for, control or benefit from them?
Opening bank accounts, expanding mobile money services and increasing loan disbursements are important milestones. However, these indicators do not necessarily tell us whether women have gained meaningful control over financial resources. Access without the ability to make decisions can leave the underlying barriers to economic participation unchanged.
Financial institutions must therefore examine not only who accesses their products, but also how their systems influence women’s ability to participate. Lending requirements should be transparent, consistent and based on applicants’ business potential and ability to repay. Women should receive information directly and make financial decisions without unnecessary demands for the consent of husbands or male relatives.
There is also a need to rethink conventional approaches to collateral. Land ownership should not be the only indicator of creditworthiness. Cash-flow assessments and appropriate movable assets can help financial institutions identify viable entrepreneurs who may not have conventional property to pledge.
Product design is equally important. Agriculture, for example, operates within seasonal production cycles. Farmers invest in land preparation, seeds, inputs and labour long before generating income from a harvest. Financial products and repayment schedules must reflect these realities. Young entrepreneurs also need financing that recognises the different stages of business development, including the time required for new enterprises to become profitable.
For women with disabilities, inclusive financial services must go beyond policy commitments to ensure that banking facilities, communication channels and customer support are genuinely accessible.
However, financial institutions cannot address these challenges alone. Families, community leaders, government, business associations and development programmes all influence the environment in which women participate economically. Changing attitudes towards women’s ownership of assets and control over earnings requires conversations that involve both men and women. Financial independence should be recognised as part of building stronger households and more productive communities.
Financial literacy is another important consideration. Women need the knowledge to evaluate financial products, understand borrowing obligations, manage their earnings and make informed investment decisions. But financial education cannot compensate for discriminatory lending practices or social expectations that restrict women’s choices. Knowledge must be matched by an enabling environment.
Through SAYE, Financial Sector Deepening Uganda works with financial institutions and other partners to improve young people’s access to finance and business opportunities in Busoga. The project aims to reach 250,000 young people, with 70 per cent being female and 3 per cent being persons with disabilities. This work includes connecting young entrepreneurs to financial service providers and supporting efforts to make financial products and services more responsive to their needs.
Such approaches are important because entrepreneurs need more than capital. They also need business knowledge, market connections and opportunities to strengthen their enterprises. Agri-hubs and business groups can help bridge these gaps by connecting farmers to practical advice, markets and financial services. Financial institutions can work with these structures, including through agent banking, to bring services closer to rural entrepreneurs.
Equally important is how we measure progress. Financial inclusion programmes should look beyond the number of people trained, accounts opened or loans disbursed. They should examine who applies for finance, who gets approved, what terms borrowers receive and whether the financing contributes to business growth and more secure livelihoods. Tracking these outcomes across sex, age and disability can help identify persistent inequalities and inform better institutional responses.
My journey from cultivating one acre to managing four acres has shown me what access to finance can make possible. But I recognise that credit alone does not guarantee success. Women also need access to productive assets, markets, skills and the freedom to make decisions about their economic activities.
I am not asking for a separate financial system for women. I want an existing system that works fairly for people with different circumstances, businesses and starting points. A woman who accesses a loan, repays it and expands her enterprise is not asking for special treatment. She is demonstrating what becomes possible when her capabilities are recognised and her economic choices are respected.
A loan can provide the capital to grow a business. But real financial inclusion is achieved when women can access finance fairly, decide how to use it, control the returns and build on what they earn. In other words, access opens the door, but the freedom to decide is what makes financial inclusion meaningful.
